Nathan Barry launched ConvertKit on January 1, 2013 as a public “Web App Challenge,” and the whole thing was built around a benchmark: get to $5,000 MRR in six months. He missed it. By June of that first year the business was at about $2,000 in monthly recurring revenue and then stopped moving, while his ebook business was pulling $200,000 to $250,000 a year. By October 2014, MRR had gone backwards to $1,207, and an advisor told him to shut it down.
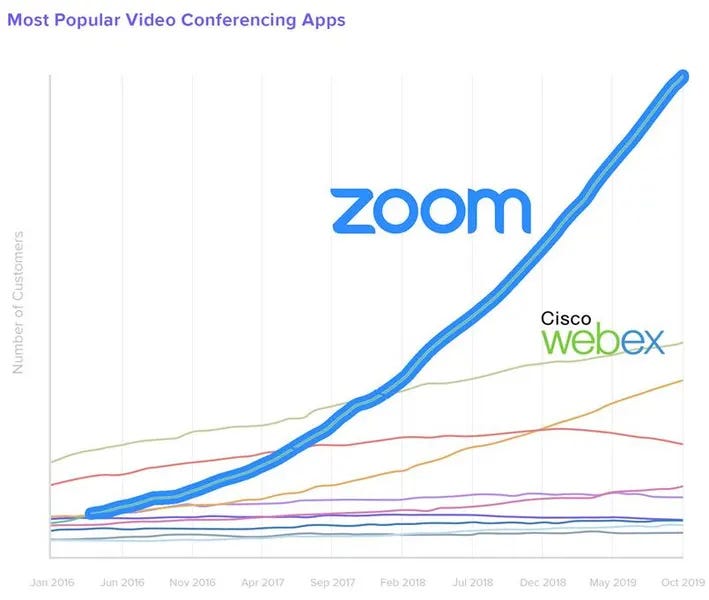
Every number in that story looks like failure if you hold it next to a venture-backed SaaS company on a hockey stick. Held next to the actual comparison set, a bootstrapped tool with one developer serving a niche audience, it looks like a company that hadn’t found its buyer yet.
Barry put $50,000 of his own savings in, killed the profitable course business that was distracting him, and started emailing bloggers one at a time. By March 2015 he was at $5,020 MRR, by June $10,000, and by December about $97,000. Ten years later Kit is past $43 million ARR with 99.5% net dollar retention, still bootstrapped and profitable.
The interesting part isn’t the turnaround. It’s that the near-shutdown was triggered by a scoreboard borrowed from companies that had nothing structurally in common with his.
The comparison you inherited is a marketing artifact
You didn’t choose your benchmark. You absorbed it. The numbers that circulate loudest are the ones somebody had a reason to publish: a funding announcement, a milestone post, an ARR screenshot that performs well on LinkedIn. That’s a filtered sample of a filtered sample.
Meanwhile the median operator in your position is invisible on purpose. One 2026 benchmark set puts the share of SaaS companies self-funding their growth at 43%. Nearly half the field isn’t raising, isn’t announcing, and isn’t posting. If your reference points are all companies that raised, you’ve quietly opted into comparing yourself against the loudest 5% of a different game.
It also cuts the other way, and this is the part founders miss. Bad benchmarks don’t just make you feel behind. They make you feel fine when you shouldn’t. Monthly churn for startups under $1 million ARR runs around 5% to 7% in 2026 benchmark data, against 0.5% to 1% for enterprise SaaS on large contracts. A founder holding the enterprise number panics over churn that’s normal for their stage. A founder holding the startup number shrugs at churn that’s actually killing them. Same data, opposite errors, both caused by pulling a comp off the shelf without checking whether it describes your business.
Pick three, then stop looking
Here’s the exercise. It takes twenty minutes and it’s more useful than any dashboard you’ll build this quarter.
Choose three companies you’ll measure against. Three, not a category. To qualify, a company has to match you on all of the following:
Same funding logic. Bootstrapped and venture-backed companies are optimizing for different outcomes with different constraints. A company burning capital to buy growth isn’t doing a harder or easier version of your job, it’s doing a different one. Comparing across that line tells you nothing you can act on.
Same buyer and price point. A $40-a-month prosumer tool and a $40,000 annual enterprise contract have different churn, different sales cycles, different everything. Retention numbers are almost meaningless across that gap.
Same age, roughly. Not the same size, the same age. “Where were they 18 months in” is a question you can answer and learn from. “How big are they now” is a question that only produces feelings.
Then write down what each of the three actually did between the stage you’re at and the stage you want. Not their current metrics. Their next move. That’s the only part that’s transferable.
Benchmark the decision, not the number
Once you have your three, use them to make one decision at a time. Change pricing, or activation, or your annual plan offer, and then check the effect at 30, 60, and 90 days before touching anything else. Comparison is only worth anything if it terminates in a decision. If a number can’t change what you do next week, it’s not a benchmark, it’s a mood.
And be honest about what stage-appropriate looks like this year, because it moves. Startups.com puts the typical pre-seed range at roughly $250K to $1.5M, with some rounds up to about $2M for hot AI and deep-tech teams, and Carta’s State of Pre-Seed report published in February 2026 shows median post-money SAFE caps of about $10M for $250K to $1M rounds and about $15M for $1M to $2.5M. One 2026 dataset has the median pre-seed check up from $750K in 2023, driven partly by pre-seed funds raising larger vehicles and the line between pre-seed and seed continuing to blur. A raise that felt small two years ago may be median today. You cannot know that from vibes.
Barry’s advisor wasn’t wrong about the number. $1,207 a month was a real number and it was going the wrong direction. He was wrong about what the number meant, because the meaning depends entirely on what you compare it to. Choose that deliberately, in writing, before you’re in a bad month and looking for evidence.
The founders who quit early rarely quit because the business failed. They quit because they were losing a race they never entered.
Inpaceline OS keeps your actual numbers in one place, so when you do sit down to compare, you’re working from your business instead of your memory of it. Start at inpaceline.com.